Build your credit score with the Classic Card
Join over 4 million people approved for the Capital One Classic Card.
No impact on your credit score
34.9% APR representative variable. Not using your card responsibly could hurt your credit rating, making it harder to get credit in future.
What is a credit builder credit card?
Credit builder cards are designed for people who have a low credit score or bad credit history. They typically have lower starting credit limits, so you can build your score safely over time by making regular payments.
Who are credit builder cards for?
First-time credit users
Credit builder cards come with smaller, more manageable credit limits than other credit cards. This can make them easier to keep track of.
Credit rebuilders
Because credit builder cards typically have smaller credit limits, you could have a better chance of approval if you’ve struggled with credit in the past.
Remember, not using your card responsibly could hurt your credit rating, making it harder to get credit in future.
First credit card? Here’s how to build credit from scratch
If you’re 18+ and have never borrowed money, you might have what lenders call a ‘thin’ credit history. This doesn’t necessarily mean you have a bad credit file, it just means lenders don’t know enough about you.
A Capital One Classic Card can help to change that. Using it for everyday spending, like the weekly shop or streaming subscriptions, can build you up a good track record of responsible spending (as long as you make your payments on time).
The Classic Card
Our most popular card with over 4 million people accepted.
- Build your credit score over time
- Know if you're accepted before you apply
- Manageable credit limits starting from £200
Building your credit score with the Classic Card
Once your card arrives, there are lots of little things you can do to improve your credit score.
Pay on time every month
Making payments before your due date shows you can use your card responsibly.Use your card
Responsible purchases and regular repayments are the key to healthy credit.Stay well under your limit
Avoid maxing out your card by leaving a comfortable buffer on your limit.Pay over the minimum
If you can afford to, make payments over the minimum monthly amount.Avoid missed payments
Try setting up a Direct Debit to make sure you never forget a payment.Look after other accounts
Applying these rules to other types of credit will help your score.
No impact on your credit score
FAQs about credit builder cards
Can I be pre-approved if I have past CCJs or defaults?
It depends on your current circumstances. A CCJ (County Court Judgment) or defaulted account in the past doesn’t automatically mean you’ll be declined, but it will be taken into consideration if it was in the last 6 years.
Can I get a credit limit increase with a credit builder card?
Yes, it’s possible. We check accounts regularly for credit limit increases. To be considered for one, the best thing you can do is manage your card well. That means paying on time and making over the minimum payment if possible.
Will checking my eligibility leave a mark on my credit file?
No, it won’t. Checking your eligibility is what’s known as a ‘soft-search’. That means that other lenders can’t see it on your credit file. If you do go on to apply, that’s when a full credit search happens, which does appear on your credit file.
Do I need to carry a balance and pay interest to build my credit score?
No, you don’t. Depending on your situation, paying your full balance off every month can be better for your score than carrying one over. Plus, you won’t pay any interest when you pay your full balance on time. So don’t worry, you never need to pay interest to prove you can borrow safely.
Can I get approved for a card if I’m 18 with no credit history?
It depends on your circumstances. Credit builder cards are designed for people with little to no credit history, so if your finances are in order, you could still be approved.
Can I get a credit builder card if my income changes month to month?
Of course. We look at your overall finances, not just one month’s pay. When you check your eligibility, think about what your average monthly income is, then multiply it by 12 to get your annual income.
What happens if I’m not eligible for a credit builder card?
If you’re not eligible this time, don’t worry. If you want, we can keep checking each month to see if you become eligible for a card. In the meantime, keep on managing your finances well to improve your chances.
What to expect from a Capital One credit card?
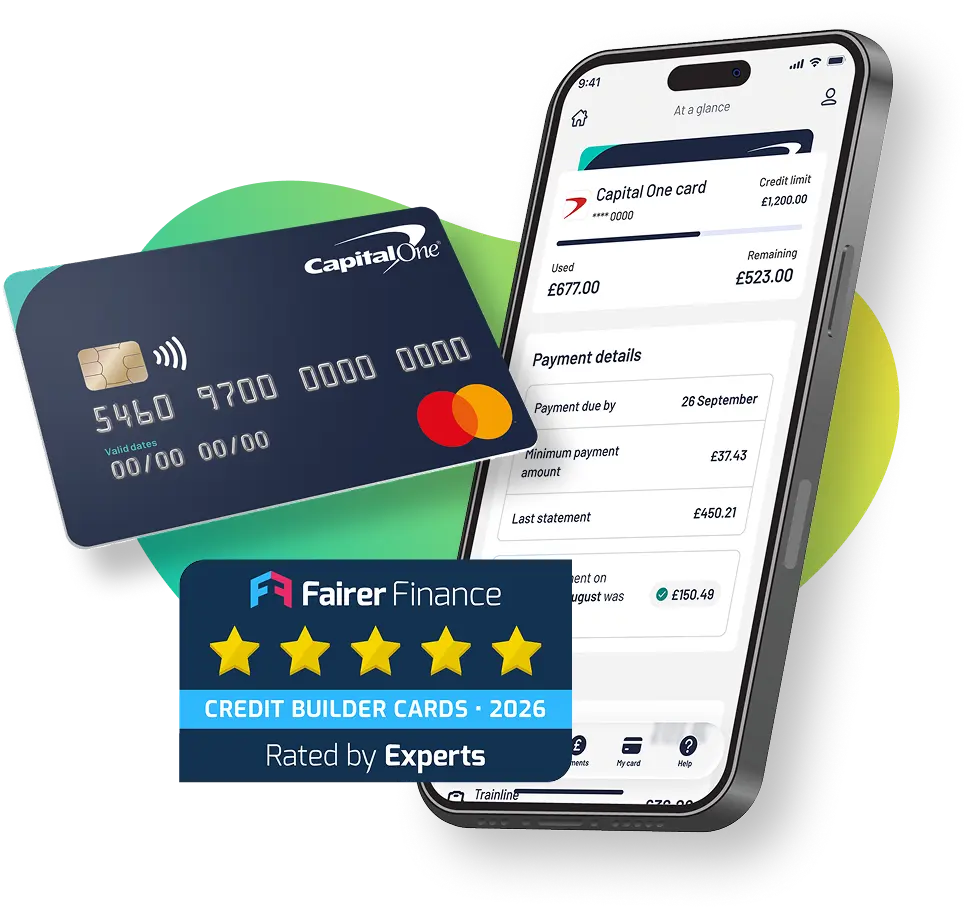
Know if you’re eligible before applying
Check if it’s a yes or no in about 60 seconds, with no impact on your credit score.
No yearly fees or nasty surprises
What you see is what you get. We’ll never charge you an annual fee, plus the APR you’re offered is always the one you’ll get.
Extra protection on purchases
All credit card purchases over £100 (like a big shop or birthday presents) are legally covered by what’s called Section 75. That means if something goes wrong, you could get the money back.
34.9% APR representative variable
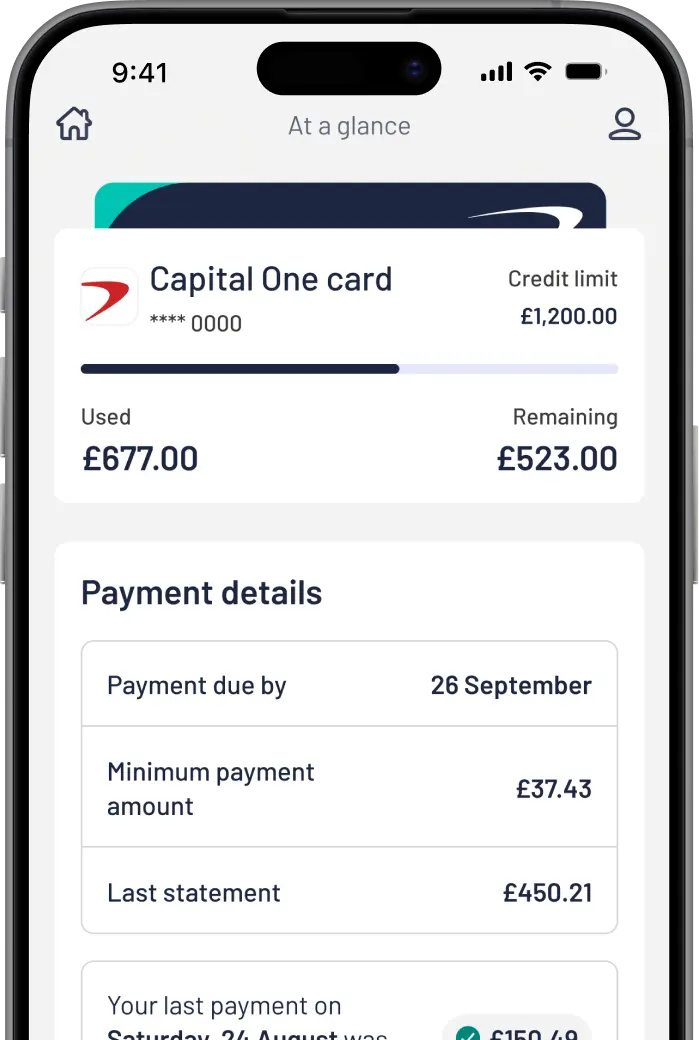
See if you’re eligible for a credit builder card
It only takes a few minutes and won’t impact your credit score.
Tell us about yourself
Fill in a few details and we’ll let you know if you’re eligible, without affecting your credit score.Get a straight yes or no
We’ll tell you if you’ll be accepted on the spot, so you can decide if you want to apply.Apply for your card
If you’re eligible and you think the card’s right for you, you can apply in one tap of a button.
No impact on your credit score
Representative example: Assuming a credit limit of £1,200 and an interest rate on purchases of 34.94% p.a. variable, you will receive a 34.9% APR representative variable.
Credit card blogs

How to build your credit score with a credit card
Take a look at this Capital One UK guide to discover how you can use a credit card to build your credit score.
What is a credit limit?
A credit limit is the maximum amount you can borrow on your credit card. Learn more about how these limits work.
How long does it take to improve your credit score?
How long it takes to improve your credit score depends on where you’re starting from and the habits you build from here. Discover some top tips for improving.